PROJECT OVERVIEW
Project Glow: Pre-Seed Diligence, Fresh Staples Q-Commerce
Investment Memorandum: Sunward Growth Advisory · Delivered 2 August 2026 · Published in redacted form
1. The Problem We Were Solving
Sunward was looking at a pre-seed company in vertically integrated fresh staples: milk, fruit and vegetables, and bread, made in the city and delivered in minutes. The deck read well. The brief was to find out whether it survived contact with its own numbers.
A pre-seed round is priced on conviction rather than evidence, so the useful question is not "is this attractive" but "what would have to be true, and which of those things can be checked today". We built the memo around that second question.
2. The Method: Five Falsification Gates
Rather than scoring the opportunity, we set five gates in the order they bind. A company that fails an early gate does not get rescued by a later one, so the ordering carries the argument.
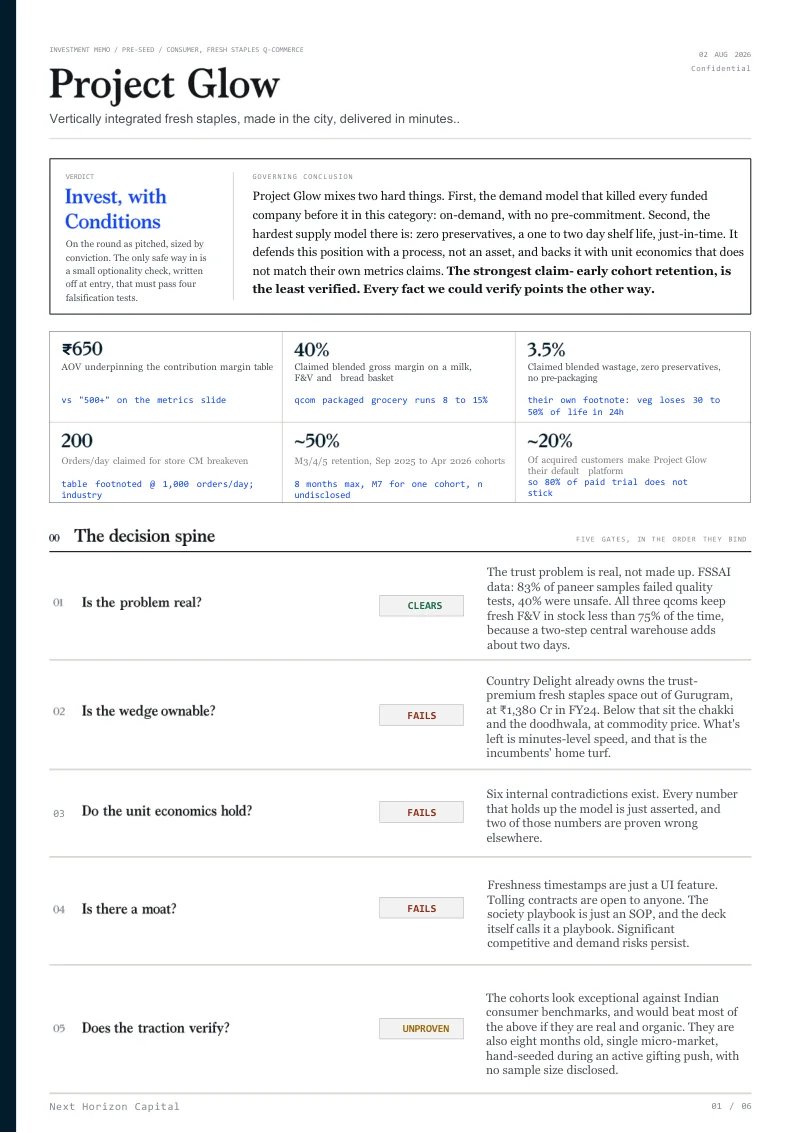
| Gate | Question | Result |
|---|
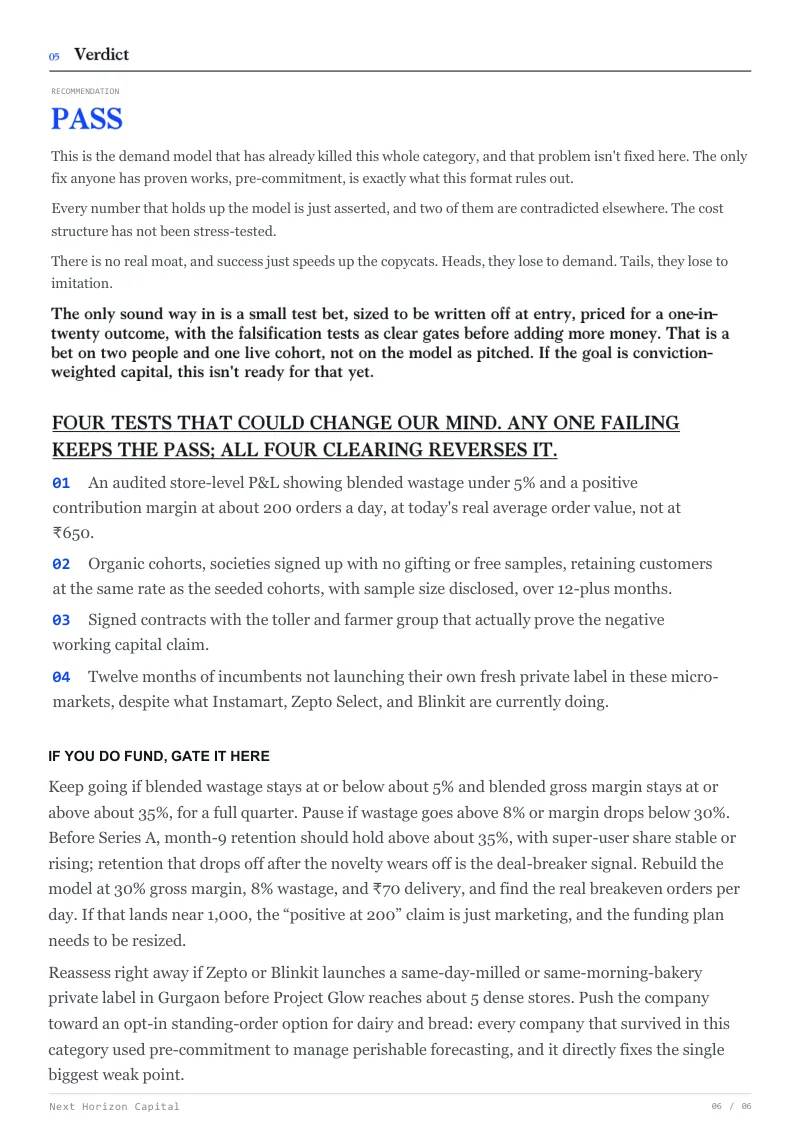
| 01 | Is the problem real? | Clears |
| 02 | Is the wedge ownable? | Fails |
| 03 | Do the unit economics hold? | Fails |
| 04 | Is there a moat? | Fails |
| 05 | Does the traction verify? | Unproven |
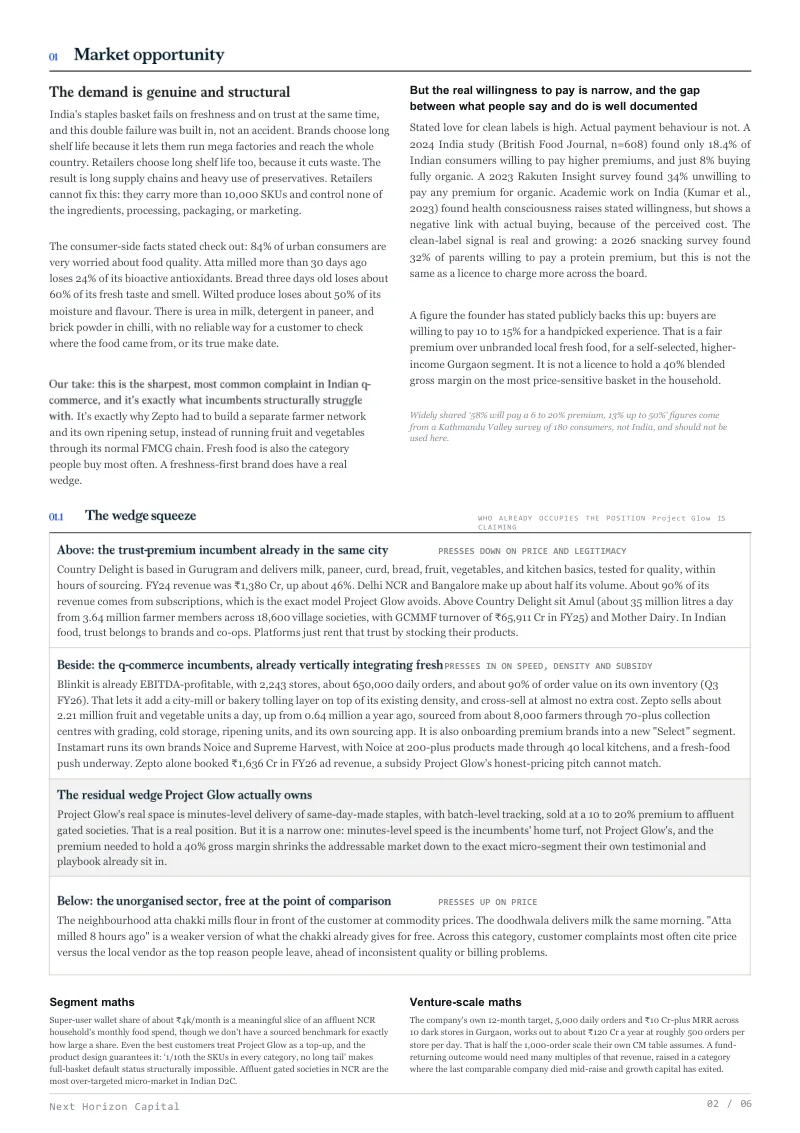
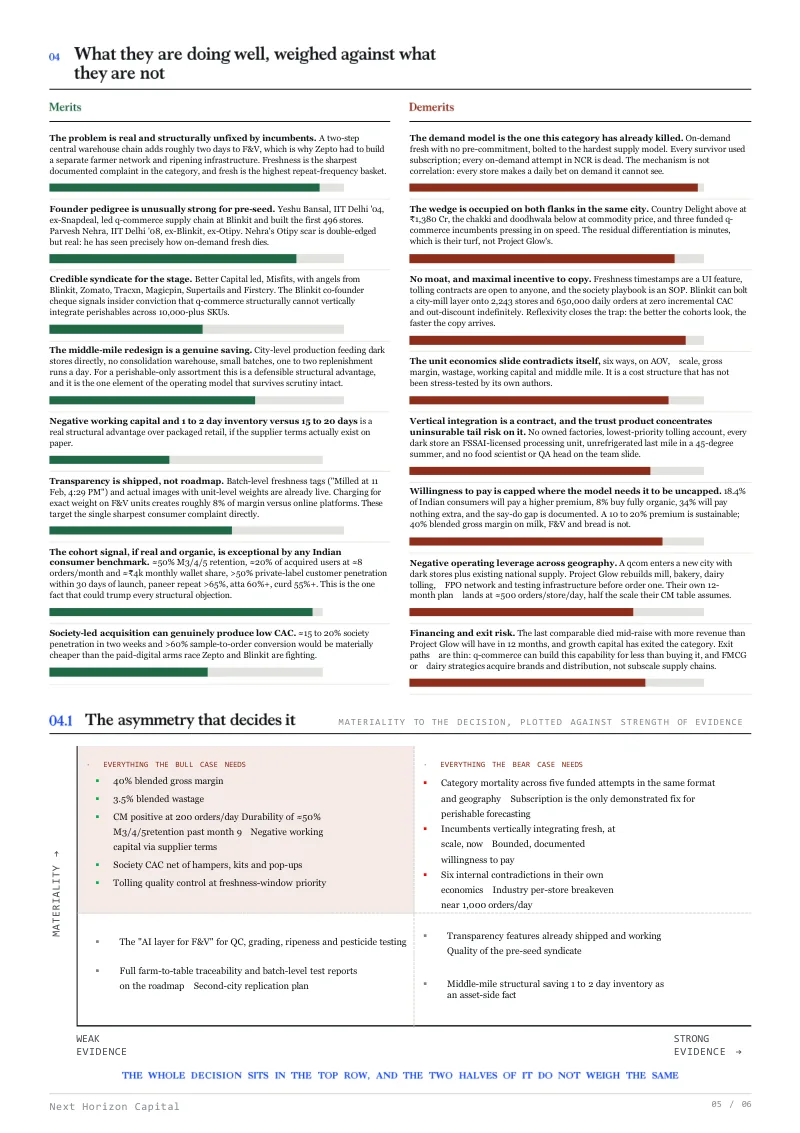
Gate 01 clears on external evidence, not on the company's framing: FSSAI sampling showed 83% of paneer samples failing quality tests and 40% unsafe, and the incumbent quick-commerce platforms hold fresh produce in stock less than 75% of the time because a two-step central warehouse adds roughly two days. The trust problem is real and is not manufactured by the pitch.
The gates that follow are where it breaks. The premium fresh-staples position is already held, leaving minutes-level speed as the wedge, which is the incumbents' home turf. The moat rests on freshness timestamps that are a UI feature, tolling contracts open to anyone, and a society-level playbook the deck itself calls a playbook.
3. Where the Numbers Disagreed With Each Other
Six internal contradictions sat inside the model. In each case the figure carrying the economics was contradicted by the company's own material elsewhere in the same deck.
| Claimed | Contradicted by |
|---|
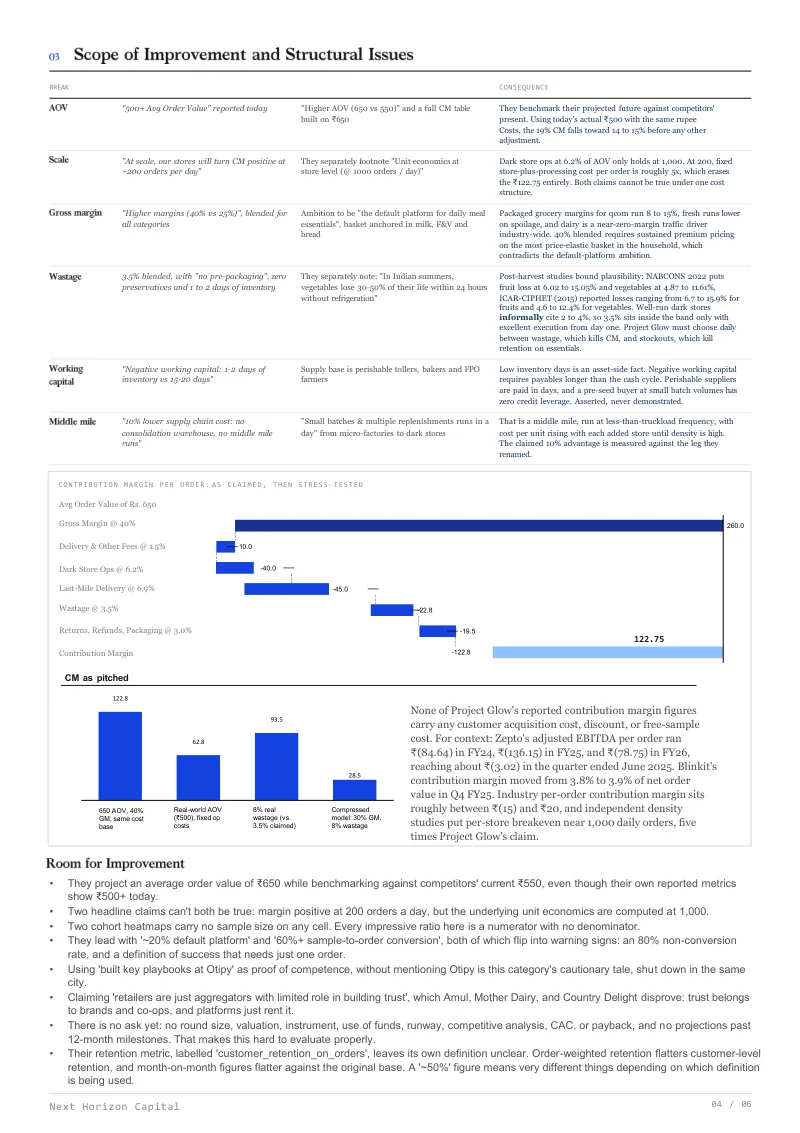
| ₹650 AOV underpinning the contribution margin table | "500+" on the company's own metrics slide |
| 40% blended gross margin on a milk, produce and bread basket | Quick-commerce packaged grocery runs 8% to 15% |
| 3.5% blended wastage, zero preservatives, no pre-packaging | Their own footnote: vegetables lose 30% to 50% of life in 24 hours |
| 200 orders per day for store contribution-margin breakeven | The same table footnoted at 1,000 orders per day |
Retention was the strongest claim in the deck and the least verified: roughly 50% M3 to M5 across cohorts, against an acquired base where about 20% make the platform their default, which puts 80% of paid trial outside the retained cohort. The cohorts were eight months old, drawn from a single micro-market, hand-seeded during an active gifting push, with no sample size disclosed.
4. The Governing Conclusion
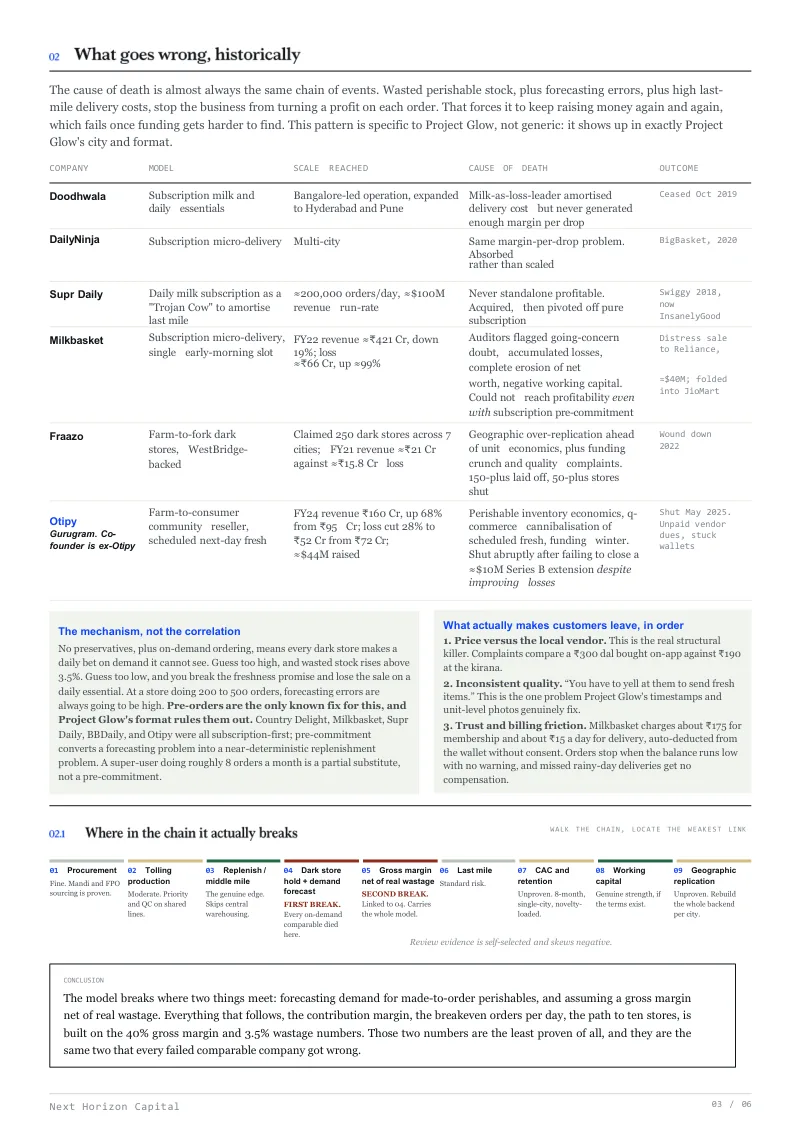
The company combines the demand model that has killed every funded company before it in this category, on-demand with no pre-commitment, with the hardest supply model available: zero preservatives, a one to two day shelf life, and just-in-time production. It defends that position with a process rather than an asset, and backs it with unit economics that do not match its own metrics claims.
Verdict: invest, with conditions. The round as pitched is sized by conviction rather than evidence, so the only defensible entry is a small optionality cheque written off at entry, conditional on four named falsification tests being passed first.
5. Methodology Principles
- Falsify, do not score: gates are ordered so an early failure is not offset by a later strength
- Check the deck against itself: most contradictions here were internal, not external
- Separate the real problem from the proposed solution: a genuine problem does not make a specific wedge ownable
- Name the verdict: a memo that does not commit is not a memo
6. Hard Constraints
- Published in redacted form. The target is referred to throughout by its project codename, and figures identifying the company or Sunward's position have been removed
- This is a research memorandum only: not investment advice and not a recommendation to transact
- Next Horizon Capital is not a SEBI-registered Investment Adviser, Research Analyst, Merchant Banker or Portfolio Manager
- All figures are point-in-time as at August 2026 and were not re-verified after delivery
Project completed and delivered. Next Horizon Capital × Sunward Growth Advisory.
← All mandates
 Completed